1. Introduction
Modern cross-border corporate structures increasingly operate within a framework that balances legitimate corporate privacy with regulatory transparency. Companies may have different legal owners, holding companies, trusts, or other entities within their ownership structure, while regulators and financial institutions may also need to identify the natural persons who ultimately own or control the business.
Key Distinction
This distinction is reflected in the different corporate records used to document legal ownership and beneficial ownership. The Register of Members (ROM) generally records the legal owners of a company’s shares, while beneficial ownership records identify the natural persons who ultimately own or exercise control over the entity.
International Standards
The relationship between these records is becoming increasingly important for international companies. Global initiatives led by organizations such as the Financial Action Task Force (FATF) and the OECD have encouraged jurisdictions to improve the availability, accuracy, and accessibility of beneficial ownership information.
For international business owners, this means that effective corporate structuring is no longer simply about establishing ownership; it also involves maintaining clear documentation, understanding reporting obligations, and ensuring that information provided to registered agents, financial institutions, and relevant authorities remains accurate and up to date.
2. Defining the Dual-Register Framework: ROM vs. ROB
Register of Members (ROM)
The Register of Members is generally one of the core statutory records maintained by a company. It records the legal shareholders and provides information relating to their ownership interests, including the shareholder’s name and address, the number and class of shares held, the date on which the shareholder became a member, and other information required under applicable corporate legislation.
The ROM is important because it helps establish who legally holds shares in the company and may be entitled to exercise shareholder rights, including voting rights and participation in distributions where applicable.
Register of Beneficial Owners (ROB)
A Register of Beneficial Owners, where required by local law, records information about the natural persons who ultimately own or exercise control over a company. Beneficial ownership is not always determined solely by the percentage of shares held. An individual may qualify as a beneficial owner through direct or indirect ownership, voting rights, contractual rights, the ability to appoint or remove directors, or other forms of effective control.
Structural Comparison
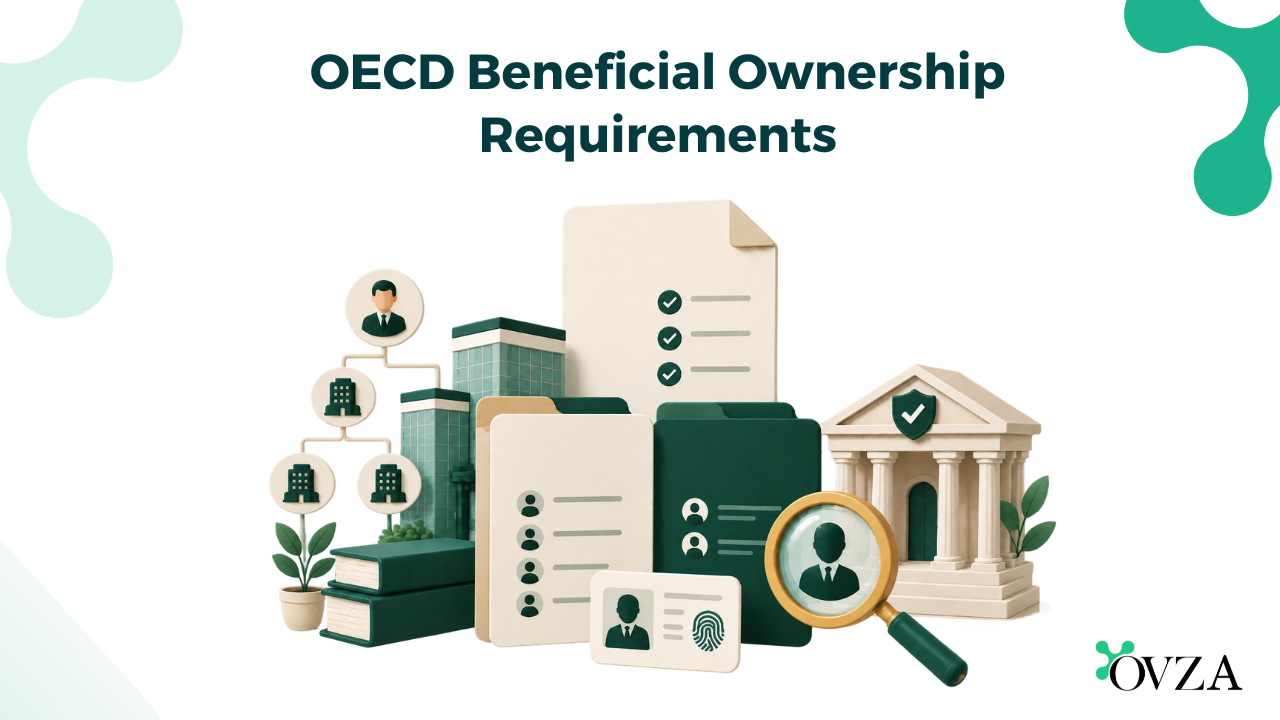
In a simple corporate structure, the legal shareholder and beneficial owner may be the same person. In more complex structures, however, ownership may pass through one or more companies, trusts, or other arrangements before reaching the individual who ultimately controls the entity. The distinction is therefore clear: the ROM answers who legally holds the shares in the company, while the ROB identifies which natural person ultimately owns or exercises control over the enterprise.
Dual-Register Operational Framework:
- Register of Members (ROM): Records legal titleholders, share classes, issue dates, and formal voting rights under domestic corporate law.
- Register of Beneficial Owners (ROB): Tracks ultimate natural persons, verified passport data, tax identification numbers, and effective control percentages for AML compliance.
- Multi-Tiered Structures: Traces intermediate holding companies, trusts, and foundations up to the living individual exercising final authority.
3. Identifying the Ultimate Beneficial Owner (UBO)
Natural Person Requirement
An Ultimate Beneficial Owner (UBO) is generally understood as a natural person who ultimately owns or exercises control over a legal entity. Under international standards, a corporate vehicle, intermediate holding company, or trust cannot be declared as the final UBO; the identification process must continue through each layer of ownership until it reaches a living human being.
The Ownership Threshold Test
International standards commonly encourage jurisdictions to identify beneficial owners using both ownership and control tests. A percentage ownership threshold may be used as a primary indicator, though the applicable threshold is determined by the relevant jurisdiction and regulatory framework. For example, a person may qualify as a beneficial owner because they directly or indirectly hold a significant ownership interest in the company, typically defined as holding more than 25% of shares or voting rights.
The Effective Control & Fallback Tests
Alternatively, an individual may exercise sufficient influence or control over the entity through non-equity mechanisms, such as voting agreements, veto rights over major operational decisions, or the power to appoint or remove members of the board of directors. Where no individual can be identified through ownership or control criteria after exhaustive searching, regulatory frameworks provide an alternative reporting approach involving the identification of senior managing officials, such as the CEO or managing director.
4. OECD and FATF International Compliance Requirements
Mandatory Obligations
International transparency standards have significantly influenced the way jurisdictions approach corporate ownership information. FATF Recommendation 24 focuses on the transparency and beneficial ownership of legal persons, mandating that countries ensure adequate, accurate, and up-to-date beneficial ownership information is accessible to competent authorities. Domestic legal systems implement these global principles as mandatory statutory requirements that companies must fulfill to maintain valid registration.
Data Verification & AEOI
Under modern compliance standards, self-declarations alone are insufficient; registered agents and company registries are required to verify identification details against primary source documentation.
Furthermore, through mechanisms established by the OECD Global Forum, beneficial ownership information is subject to international frameworks such as the Automatic Exchange of Information (AEOI) and the Common Reporting Standard (CRS), allowing tax authorities to share relevant ownership data across borders.
Prohibition of Secrecy Tools
To eliminate regulatory blind spots, global standards strictly restrict or prohibit traditional secrecy mechanisms. Bearer shares must be immobilized or converted into registered shares, and unrecorded nominee arrangements are prohibited. Nominees must disclose their status and report the identity of their underlying nominators to the relevant corporate service provider or statutory register.
5. Maintaining a Compliant UBO Workflow
Ownership Mapping
A practical beneficial ownership compliance process begins with a clear understanding of the company’s ownership structure. Companies should maintain an updated ownership chart that identifies each legal entity or individual in the chain between the operating company and the natural persons who ultimately own or control it. Ownership percentages, voting rights, and other relevant control mechanisms should be reviewed against the legal requirements of the jurisdiction.
Ongoing Maintenance & Reporting Deadlines
Supporting documentation such as passport copies, proof of residential address, corporate documents for intermediate entities, and agreements explaining control mechanisms must be retained in accordance with legal standards.
When structural changes occur, such as a transfer of shares, changes in directorship, or adjustments to beneficial ownership, companies must review whether their statutory records require updating. Reporting deadlines for updating beneficial ownership information vary by jurisdiction, typically requiring notifications within 15 to 30 days of any material change.
6. Commercial Reality: Private Status vs. Financial Account Disclosures
Private Company Standing vs. Public Disclosures
Maintaining a private company allows business owners to keep their commercial arrangements, internal contracts, and operational decisions confidential from competitors and the general public. In many international financial centers, beneficial ownership registries are non-public, meaning that public corporate records display only the registered agent, corporate officers, or holding companies rather than publishing the UBO’s personal details online.
Mandatory Submissions for Banking and Trading Accounts
However, private entity status does not exempt a company from financial transparency when accessing institutional banking infrastructure. To open or maintain a corporate bank account, brokerage account, or merchant trading account, financial institutions legally require full disclosure of the company’s Ultimate Beneficial Owners (UBOs). Under strict Anti-Money Laundering (AML) laws, banks will not activate accounts without receiving certified UBO documentation, complete ownership charts, notarized passports, and verified proofs of address.
The Role of Compliant Record-Keeping in Financial Approvals
Attempts to withhold UBO disclosures from financial institutions inevitably result in account rejection, frozen funds, or account termination. Maintaining accurate, pre-verified Registers of Members (ROM) and Registers of Beneficial Owners (ROB) ensures that a private entity can satisfy institutional onboarding requirements efficiently, allowing the business to maintain commercial privacy from the public while securing necessary banking and trading capabilities.
Conclusion
Evaluating the relationship between the Register of Members (ROM), beneficial ownership records (ROB), and OECD/FATF transparency standards is a fundamental aspect of managing a modern cross-border enterprise. While the ROM documents legal ownership of share capital, beneficial ownership records verify the natural persons who exercise ultimate economic control. Establishing an organized corporate structure backed by accurate supporting documentation ensures long-term regulatory compliance while preserving legitimate operational privacy.
Add OVZA to Google Preferred Sources
Make OVZA your preferred source to ensure you can easily discover our latest insights, research, and trusted content directly through Google.
Disclaimer: The information provided on this website is intended for general reference and educational purposes only. While OVZA makes every effort to ensure accuracy and timeliness, the content should not be considered legal, financial, or tax advice.