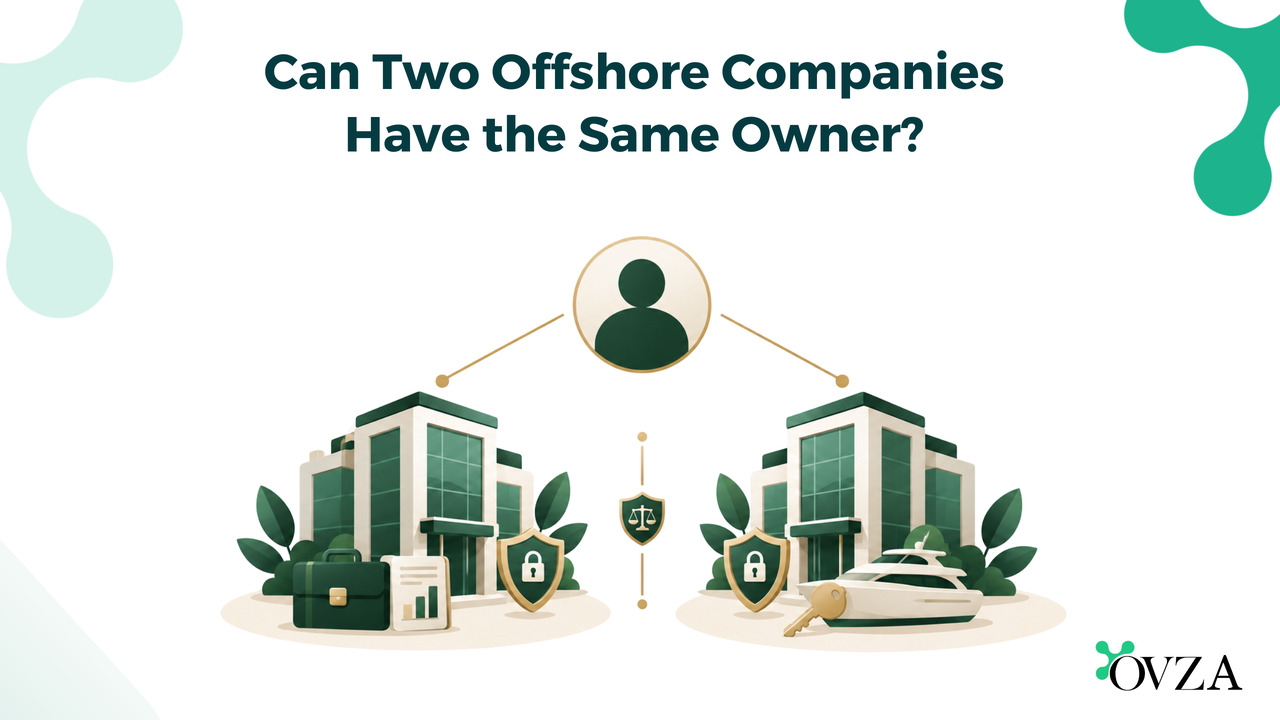
Establishing cross-border corporate frameworks frequently involves structuring multiple entities to manage diverse commercial operations and high-value assets efficiently. A single natural person or corporate holding entity can legally own and control multiple offshore companies simultaneously across different international jurisdictions. Operating multiple entities under common ownership is a standard commercial practice utilized by high-net-worth individuals, family offices, and multinational enterprises. This approach allows investors to segment commercial risks, optimize cross-border capital allocation, and satisfy varying regulatory requirements across distinct commercial sectors.
While the ultimate controlling party remains identical across the portfolio, each offshore company exists as a distinct legal person with independent statutory obligations. Maintaining separate entities requires strict adherence to corporate governance protocols, separate accounting procedures, and independent statutory registers. Failing to properly segregate the operations of commonly owned companies can compromise asset protection frameworks and trigger legal invalidity across corporate actions. Professional administration ensures that the entire corporate group remains fully operational under applicable company law.
Strategic Asset Ring-Fencing and Risk Segregation
The primary legal advantage of establishing multiple offshore companies under common ownership is strategic asset ring-fencing. Mixing high-risk commercial trading operations with high-value passive assets such as real estate, intellectual property, or aviation assets exposes the entire portfolio to consolidated litigation risks. Allocating discrete assets into independent Special Purpose Vehicles (SPVs) ensures that liabilities generated by one entity cannot legally encumber the assets held by another. This segregation isolates operational hazards within clearly defined corporate boundaries.
If a commercial trading entity encounters financial insolvency, creditor claims, or contractual disputes, the legal liability remains strictly confined to that specific company. A sister company holding the owner’s superyacht or private equity investments remains legally insulated from the trading company’s creditors. This structural segregation protects the owner’s broader personal and commercial wealth while allowing diverse global operations to function simultaneously without cross-contamination.
Corporate Group Architecture: Sister Companies vs. Holding Structures
Common ownership can be structured horizontally through sister companies or vertically through a centralized holding company architecture. In a horizontal structure, the beneficial equity owner holds direct personal shares in multiple independent entities, such as a British Virgin Islands business company and a Seychelles trading firm. This direct ownership model simplifies dividend distributions but requires the owner to manage multiple independent statutory compliance profiles directly across different corporate registries.
Alternatively, a vertical holding structure utilizes a master offshore holding company that owns the shares of underlying operational subsidiaries. The principal holds equity only in the parent holding company, which centralizes dividend accumulation, corporate voting control, and international wealth succession planning. Both architectural models require precise documentation on the statutory Register of Members (ROM) to establish clear legal title for each distinct corporate vehicle within the broader group structure.
Statutory Register Management and Corporate Maintenance
Owning multiple offshore entities requires maintaining distinct statutory registers for every incorporated legal vehicle within the corporate group. Each entity must maintain its own independent Register of Directors (ROD), Register of Members (ROM), and corporate seal records at its designated registered office. The corporate service provider must ensure that board resolutions, shareholder approvals, and annual license fees are managed separately for every company in the portfolio.
Where commonly owned entities operate across different international financial centers, each entity must comply with the specific filing deadlines and statutory renewal rules of its host jurisdiction. Annual return filings, corporate secretary maintenance, and economic substance declarations must be executed independently for every company. Failing to maintain separate statutory files can result in administrative strike-off, loss of corporate Good Standing, or invalidation of corporate signing authority.
Furthermore, corporate management must ensure that each entity maintains its own dedicated accounting records and financial statements. Even where financial results are consolidated at a parent holding company level, each underlying subsidiary must maintain independent general ledgers and balance sheets. Clear accounting segregation reinforces the separate legal status of each company and ensures smooth auditing across international jurisdictions.
Operational Governance and Preventing Veil Piercing
A critical legal risk for individuals owning multiple offshore entities is the improper commingling of corporate funds and administrative functions. Because each company possesses a separate legal personality, owners cannot freely transfer capital between sister companies without executing formal commercial agreements. Moving funds between commonly owned entities requires documented inter-company loans, standardized arm’s-length interest rates, and formal board resolutions approving the financial transfers.
Disregarding these strict corporate boundaries allows courts and creditors to invoke the legal doctrine of “piercing the corporate veil.” If a judicial authority determines that multiple companies operate as a single indistinguishable enterprise lacking internal governance boundaries, they may consolidate the entities’ liabilities. Maintaining distinct corporate bank accounts, separate accounting ledgers, and accurate statutory registers prevents legal consolidation and preserves the integrity of the offshore holding structure.
Conclusion
A single beneficial owner can legally establish and control multiple offshore companies to achieve advanced asset protection, risk segregation, and international commercial flexibility. Structuring separate Special Purpose Vehicles (SPVs) ensures that distinct commercial operations and high-value assets remain shielded from cross-entity liabilities. Whether operating through horizontal sister companies or a centralized holding structure, each entity must actively maintain its independent legal personality.
Executing this strategy successfully requires strict adherence to corporate governance boundaries, avoiding financial commingling, and satisfying independent statutory requirements for every active entity. Maintaining accurate Registers of Members across the entire corporate group ensures continuous legal validity and seamless commercial execution.
Add OVZA to Google Preferred Sources
Make OVZA your preferred source to ensure you can easily discover our latest insights, research, and trusted content directly through Google.
Disclaimer: The information provided on this website is intended for general reference and educational purposes only. While OVZA makes every effort to ensure accuracy and timeliness, the content should not be considered legal, financial, or tax advice.








